 Chinese (Traditional)
 Chinese (Simplified)
 English (UK)
Successfully Held The Global Family Office New Era Summit (Kuala Lumpur)
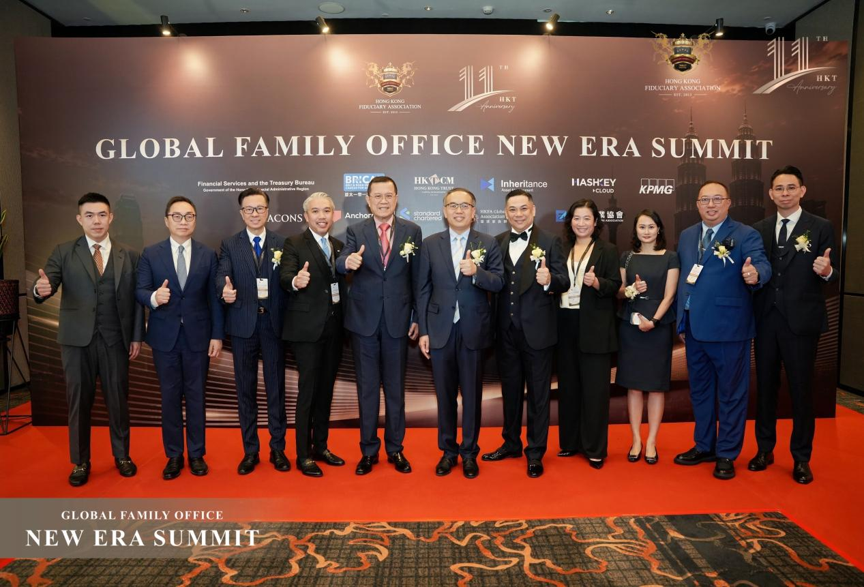
On 22 July, Hong Kong Fiduciary Association Limited successfully held the “Global Family Office New Era Summit” in Kuala Lumpur, Malaysia. Under the theme “Honouring Legacy, Shaping Tomorrow”, this summit gathered leading figures from the global wealth management sector and was dedicated to establishing a high-quality platform for exchange and cooperation within the international wealth management industry. Scenes from the Global Family Office New Era Summit. In recent years, as the global wealth management landscape has continued to evolve, family offices have become a key vehicle for wealth inheritance. Leveraging its strengths as an international financial centre, a well-developed professional ecosystem and its strategic location, Hong Kong is emerging as a major hub for the development of family offices in Asia. Recent data shows that the number of single family offices in Hong Kong has surpassed 3,300, more than half of which have assets under management exceeding US$51 million, further cementing Hong Kong’s position as Asia’s leading family office hub. Against this rapid growth, nearly 300 political and business leaders, wealth management experts, and industry representatives gathered to discuss what lies ahead for the sector. Hong Kong Fiduciary Association Limited invited senior government officials including The Honourable Christopher Hui, Secretary for Financial Services and the Treasury of the Government of the Hong Kong Special Administrative Region, and also Tan Sri Dato Sri Ong Tee Keat, Former Minister of Transport, Malaysia and President of Belt and Road Initiative Caucus for Asia Pacific (BRICAP), to attend our summit and deliver keynote speeches for us. The summit also gathered representatives from the world’s leading professional organisations, including local law firm in Hong Kong with a century of history – Deacons; One of the world’s Big Four accountancy firms – KPMG; Licensed digital asset trading platform in Hong Kong – HashKey Cloud; Licensed trust services provider – Hong Kong Trust Capital Management Limited; and also Inheritance Asset Management Limited with Hong Kong Securities and Futures Commission License Type 4 & Type 9. The experts engaged in in-depth discussions on cutting-edge topics such as global wealth management, cross-border financial cooperation, digital assets, development of stablecoins and innovations in trust services, and jointly explored development opportunities for family offices in the new era. Group photo of guests at the Global Family Office New Era Summit. As a major industry event transcending geographical boundaries, this summit not only witnessed in-depth exchanges between Hong Kong, China and Malaysia in the fields of finance and wealth management, but also reflected the shared aspirations of the Asia-Pacific family wealth management sector for high-quality development. Government and business leaders gathered in Kuala Lumpur to discuss development opportunities for global family offices At the beginning of the summit, Mr. Mong Chung Chee, President of Hong Kong Fiduciary Association Limited in Asia Pacific region, delivered the speech on behalf of the organiser. He noted that, as the global wealth management landscape continues to evolve, Hong Kong has been steadily strengthening its competitive edge as an international family office hub, thanks to its mature common law system, status as an international financial centre and well-developed professional services ecosystem. Under this circumstance, Hong Kong Fiduciary Association Limited will continue to leverage its strengths as an international platform to gather global professional institutions and high-quality resources, thereby driving innovation and development within the family office sector and creating more opportunities for cross-border collaboration and international growth for entrepreneurs and high-net-worth individuals. Mr. Mong Chung Chee, President of Asia Pacific Region at Hong Kong Fiduciary Association Limited, delivered the welcome speech on behalf of the organiser. Subsequently, The Honourable Christopher Hui, Secretary for Financial Services and the Treasury of the Government of the Hong Kong Special Administrative Region, delivered a keynote speech entitled “Bringing Certainty to Uncertainty: Hong Kong’s Edge as a Family Office Hub”. In his address, he assured attendees that, with its robust regulatory framework, forward-looking fiscal system and long-standing position as a premier global family office hub, Hong Kong is undoubtedly their “anchor of stability” amid global headwinds. Mr. Christopher Hui, Secretary for Financial Services and the Treasury of the Hong Kong Special Administrative Region, delivered the Summit’s keynote address. Tan Sri Dato’ Sri Ong Tee Keat, former Minister of Transport, Malaysia and President of Belt and Road Initiative Caucus for Asia Pacific (BRICAP), delivered a keynote speech on: “Bridging Prosperity through Synergy between Hong Kong and Malaysia in the New Era”. Tan Sri Dato’ Seri Ong Tee Keat, Former Minister of Transport of Malaysia and President of the Belt and Road Initiative Caucus for Asia Pacific (BRICAP), shared insights on opportunities for synergistic development between Hong Kong and Malaysia. Against the backdrop of global wealth management’s ongoing shift towards integrated development, the summit brought together representatives from various professional fields—including law, taxation, digital finance and trust to explore the future direction of family offices from multiple perspectives, thereby offering entrepreneurs and high-net-worth individuals a more diverse range of international professional insights. Ms. Fiona Fong, Partner, Financial Services at Deacons, took a deep dive into “Governance, Licensing, and Investment Structuring: The Key Pillars of a Resilient Hong Kong Family Office” . Ms. Fiona Fong, Partner, Financial Services at Deacons, delivered a presentation on governance, licensing, and investment structures. Ms. Lorraine Cheung, Partner, Business Tax Advisory at KPMG, highlighted Hong Kong’s competitive edge in her presentation: “Hong Kong Wealth Management Advantages: Why Hong Kong!” Ms. Lorraine Cheung, Partner, Corporate Tax, KPMG, shared insights on Hong Kong’s wealth management advantages. Mr. Vincent Shang, Business Development Director of HashKey Cloud, delivered a presentation titled “Digital Assets and the Future of Family Office Portfolios”, in which he explored the rationale for allocating digital assets in family office portfolios and their future prospects. Mr. Vincent Shang, Business Director of HashKey Cloud, shared insights on the future of digital assets in family office investment portfolios. Mr. Melvin Mui, Chief Executive Officer of Hong Kong Trust Capital Management Limited, delivered an in-depth presentation on “How Can Hong Kong Trusts Meet the Diverse Needs of Global Family Offices in this New
What to Expect When Setting Up a Trust for the First Time
Why Understanding the Process Matters Before You Begin Setting up a trust for the first time can feel unfamiliar. The legal terminology, the number of decisions involved, and the range of professionals engaged can make the process seem more complex than it needs to be. However, the core steps follow a logical sequence. Understanding what to expect at each stage helps families approach the process with greater clarity and confidence. The Initial Conversation With a Trustee or Advisor The process typically begins with an initial consultation with a professional trustee or a legal advisor specialising in trust structuring. This conversation covers the family’s objectives, the assets they consider transferring into the trust, the identity of the intended beneficiaries, and any specific governance requirements the family has in mind. This initial conversation is as much about fit as it is about information gathering. The family assesses whether the trustee understands their situation, while the trustee assesses whether the proposed structure falls within their expertise. Families should therefore come prepared with a basic overview of their asset base, their family composition, and their primary objectives. Choosing the Right Structure One of the earliest decisions when setting up a trust is choosing the type of structure that best suits the family’s objectives. The most common choice for wealth planning is a discretionary trust, where the trustee holds broad powers to decide how and when to make distributions. This offers flexibility in responding to changing family circumstances over time. However, other structures may suit the family’s needs better depending on their specific goals. A fixed interest trust, where beneficiaries hold defined entitlements, may suit situations where the settlor wants more certainty about how assets will be distributed. The legal advisor and trustee can guide this decision, but the settlor should understand the key trade-offs before committing. The Hong Kong Trustee Ordinance Cap 29 provides the statutory framework within which all trust structures in Hong Kong operate. The Due Diligence Process Before setting up a trust, the professional trustee conducts thorough due diligence on the settlor and other key parties. This is a regulatory requirement under Hong Kong’s anti-money laundering framework and applies to every family, not just specific cases. It covers identity verification, source of wealth documentation, and an assessment of the structure’s purpose and intended use. Families should expect to provide identity documents, evidence of the source of funds, and information about their business or investment activities. The Anti-Money Laundering and Counter-Terrorist Financing Ordinance sets the legal framework for these requirements. The due diligence process typically takes several weeks, depending on the complexity of the family’s financial background. Drafting the Trust Deed Once the family agrees on the structure and due diligence gets underway, the legal advisor drafts the trust deed. This foundational document governs the trust’s operation. It defines the settlor, the trustee, the beneficiaries, the trustee’s powers, the distribution framework, and any special provisions such as a protector mechanism or reserved powers for the settlor. The drafting process involves several rounds of review between the legal advisor, the trustee, and the settlor. Families should engage actively with this process and ask questions about any provisions they do not fully understand. Setting up a trust with a deed that does not reflect the family’s intentions creates problems that are difficult and costly to resolve later. The STEP Society of Trust and Estate Practitioners sets professional standards for trust deed preparation. Transferring Assets Into the Trust Once the settlor executes the trust deed, assets transfer into the trust. The method depends on the nature of the asset. Cash and financial investments transfer through standard banking or brokerage processes. Property transfers may require local legal steps and may attract stamp duty. Business interests may require corporate restructuring before the trust can hold them. Setting up a trust does not automatically transfer assets into it. Each asset class requires a deliberate transfer process, and the trustee takes legal ownership at the point of transfer. Families should consequently work with their legal advisor and the trustee to plan the transfer sequence carefully, particularly where assets span multiple jurisdictions. Writing the Letter of Wishes Alongside the trust deed, the settlor typically prepares a letter of wishes. This private document addresses the trustee and provides guidance on how the settlor would like the trustee to exercise their discretion. It might address how distributions should be made to different beneficiaries, how assets should be invested, and how the settlor would like the structure to evolve over time. The letter of wishes is not legally binding, but professional trustees give it considerable weight when making decisions. It is also a living document that the settlor can update as circumstances and preferences change. Writing a clear and thoughtful letter of wishes is therefore one of the most valuable steps a settlor can take during this process. How Long the Process Takes Setting up a trust in Hong Kong typically takes between six and twelve weeks, from the initial consultation to the point at which the trust deed is executed and assets begin to transfer. The timeline depends on the complexity of the structure, the speed of the due diligence process, and the number of asset classes being transferred. Families with straightforward structures and well-documented financial backgrounds can expect the process to move relatively quickly. However, those with complex multi-jurisdictional asset bases, or assets requiring local legal steps elsewhere, should allow additional time. What Happens After the Trust Is Set Up The trust’s establishment marks the beginning of an ongoing relationship with the trustee, not the end of a one-time transaction. Afterward, the trustee takes responsibility for managing the assets, communicating with beneficiaries, making distribution decisions, and meeting all regulatory obligations. The settlor should expect regular reporting from the trustee on the trust’s performance and administration. Families should also plan for periodic reviews of the trust structure to ensure it remains aligned with their objectives as circumstances evolve. A well-drafted deed, a
Why Wealthy Families Review Their Wealth Structures Every Few Years
Why a Structure That Worked Before May Not Work Now A wealth structure is not a permanent solution. It is a framework designed to meet a family’s objectives at a specific point in time, under a specific set of legal, regulatory, and personal circumstances. As those circumstances change, the structure may become less effective, more costly to maintain, or inconsistent with the family’s current goals. Wealthy families who treat a wealth structure review as a one-time exercise at establishment risk accumulating structural inefficiencies that compound over time. Regular reviews ensure the structure continues to serve its intended purpose as the family and the world around it evolve. Family Circumstances Change The most immediate trigger for a review is a change in the family itself. Marriage, divorce, the birth of children or grandchildren, the death of a key family member, or a significant shift in a beneficiary’s financial position can all affect whether the existing structure remains appropriate. A trust deed drafted when a family had two adult children may not adequately address the interests of five grandchildren born in later years. Furthermore, changes in the residence or domicile of the settlor or key beneficiaries can affect how authorities treat the structure for tax and regulatory purposes across jurisdictions. These changes make a periodic wealth structure review essential rather than optional. Tax Laws and Reporting Requirements Evolve The international tax environment has changed significantly over the past decade and continues to evolve. The introduction of the Common Reporting Standard, updates to transfer pricing rules, and the ongoing development of digital asset tax frameworks all affect how tax authorities in different countries assess wealth structures. A structure established ten years ago may have been designed around a tax environment that no longer exists. A wealth structure review therefore assesses whether the existing arrangement remains compliant under current rules and identifies any adjustments needed to reflect legislative change. The OECD tax transparency and exchange of information portal tracks the international developments that most frequently affect cross-border structures. Regulatory Requirements for Trustees Change The regulatory environment for professional trustees has tightened considerably in recent years. Anti-money laundering obligations, beneficial ownership reporting requirements, and customer due diligence standards have all increased in scope and complexity. A wealth structure review provides an opportunity to assess whether the trustee’s current practices align with applicable regulatory standards. Hong Kong’s Anti-Money Laundering and Counter-Terrorist Financing Ordinance has been updated over time to reflect evolving international standards. Consequently, trustees must keep pace with these changes in their administration practices. The Asset Base Shifts Families accumulate, dispose of, and restructure assets over time. Business interests are sold, property portfolios change, investment strategies shift, and new asset classes such as digital assets enter the picture. A structure designed to hold a specific set of assets may not function as intended once the asset base changes materially. A wealth structure review examines whether the trust deed gives the trustee adequate authority to hold and manage the current asset base, and whether the investment mandate remains appropriate. Structures not reviewed in several years may contain provisions written for a different asset base. These create unnecessary constraints on how the trustee can act today. Governance Arrangements Need Updating Family governance frameworks age alongside the family itself. A protector appointed ten years ago may no longer be the right person for the role. A family investment committee established when the children were young adults may need restructuring as the next generation takes on greater responsibility. A regular wealth structure review addresses these governance questions directly. It ensures that the people in key roles remain appropriate, that communication channels between the trustee and the family stay functional, and that governance documents reflect the family’s current intentions rather than those of a previous era. Jurisdiction and Structure Choices Should Be Reassessed The jurisdictional landscape for wealth structuring changes over time. New information exchange agreements come into force. Political and regulatory environments shift. The relative attractiveness of different jurisdictions for trust administration evolves as laws develop. Families should therefore consider whether the current jurisdiction remains optimal and whether structural changes would improve effectiveness. The STEP Society of Trust and Estate Practitioners provides practitioners with ongoing updates on jurisdictional developments that affect these assessments. What a Review Typically Covers A comprehensive review of this kind typically covers several areas. These include a check that the trust deed remains legally effective, an assessment of the trustee’s administration practices against current regulatory standards, a review of the tax position in each relevant jurisdiction, and a discussion with the settlor and key beneficiaries about whether the structure continues to meet their objectives. The review does not necessarily result in significant changes. In many cases, it confirms that the structure remains fit for purpose with minor updates. However, identifying issues early costs considerably less than addressing them after they create legal, tax, or governance problems. How Often Families Should Review There is no universal rule for review frequency. However, most practitioners recommend a formal review every three to five years as a baseline. Additionally, reviews should follow significant events, including changes in family composition, major shifts in the asset base, a change in the settlor’s country of residence, and significant regulatory or tax law changes in relevant jurisdictions. Building a formal review cycle into the trust’s governance framework from the outset ensures that reviews happen consistently rather than only after a problem has already emerged.
What Families Should Budget for a Hong Kong Trust Administration
Why Understanding Trust Costs Matters Before You Structure Establishing a trust is a long-term commitment. Legal and administrative costs accumulate over years and sometimes decades. Families who do not understand Hong Kong trust costs before establishing a structure may face ongoing fees they did not expect. Trustees sometimes fail to communicate these fees clearly at the outset. Understanding what drives costs, what trustee fees typically include, and what additional expenses arise over a trust’s life helps families make better decisions. It also helps them select trustees whose fee models align with their expectations. How Professional Trustee Fees Are Structured Professional trustees in Hong Kong typically charge fees in one of two ways. Some charge a percentage of total assets under administration, calculated annually. This is common for trusts holding investment portfolios or significant liquid assets. Others charge a fixed annual retainer combined with hourly rates for specific transactions or decisions. The percentage-based model means fees scale with the value of the trust’s assets. A trust holding a larger asset base will therefore attract higher annual fees even if administrative complexity stays the same. Families should ask trustees to model projected fees across different asset value scenarios before committing to a structure. Establishment Costs The initial costs of setting up a trust include legal fees for drafting the trust deed and due diligence costs during onboarding. They also include any stamp duty or transfer costs associated with moving assets into the trust. In Hong Kong, stamp duty applies to the transfer of Hong Kong residential property and certain securities. Families transferring these asset classes should consequently factor stamp duty into the overall establishment cost. Legal fees for trust deed drafting vary significantly depending on structural complexity. A straightforward discretionary trust costs considerably less to draft than a complex multi-jurisdictional structure with reserved powers and a protector mechanism. The Hong Kong Law Society provides guidance on professional standards for legal service providers. However, no regulator sets fee levels themselves. Annual Administration Fees Annual administration fees cover the trustee’s ongoing responsibilities. These include maintaining trust records, preparing annual accounts, communicating with beneficiaries, and reviewing the investment portfolio. They also include meeting regulatory obligations under the TCSP licensing regime. This category of Hong Kong trust costs typically represents the largest cumulative expense over a trust’s life. Families should request a clear breakdown of what the annual fee includes and what activities attract additional charges. Some trustees include all routine administration within the annual fee. Others charge separately for each distribution decision and each beneficiary communication. Understanding this distinction before selecting a trustee is therefore important for accurate cost planning. Transaction and Distribution Fees Beyond annual administration, trustees typically charge for specific transactions. These may include processing distributions, executing investment transactions, handling property transactions, and managing regulatory reporting across jurisdictions. Distribution fees are particularly relevant for discretionary trusts where distributions occur regularly. Each decision involves the trustee reviewing the beneficiary’s circumstances, documenting their reasoning, and processing the payment. Where distributions are frequent, these transaction charges can add meaningfully to overall Hong Kong trust costs over time. Legal and Advisory Costs Over the Trust’s Life A trust does not operate in a legal vacuum. Over its lifetime, circumstances arise that require legal advice. These might include disputes between beneficiaries, questions about interpreting the trust deed, or amendments made in response to changing family circumstances. The Hong Kong Judiciary handles trust disputes that escalate to formal legal proceedings, and litigation costs can be significant. Families should understand that these costs fall outside the trustee’s standard fee structure. Furthermore, building a governance framework that reduces disputes is one of the most effective ways to manage this category of expense. Costs of Holding Assets in Multiple Jurisdictions Trusts holding assets across multiple jurisdictions attract additional costs that single-jurisdiction structures do not face. These include local legal fees for managing assets in each country and tax filing costs where the trust has reporting obligations. Banking fees for maintaining accounts in multiple currencies add a further layer of cost. For families with genuinely international asset bases, these multi-jurisdiction costs are unavoidable. However, consolidating assets within a single trust structure administered from Hong Kong can reduce duplication compared to maintaining separate arrangements in each country. The net effect on Hong Kong trust costs depends on the specific jurisdictions involved and the nature of the assets held. Comparing Costs Against the Benefits Families should always assess Hong Kong trust costs against the benefits the structure provides. A trust that consolidates cross-border assets, avoids probate across multiple jurisdictions, and ensures a governed succession framework delivers value that extends well beyond the administrative fees involved. The relevant comparison is not the cost of a trust against doing nothing. It is the cost of a trust against alternatives such as multi-jurisdiction probate and the risk of assets passing incorrectly. It also includes the administrative burden of managing assets across multiple personal accounts. The STEP Society of Trust and Estate Practitioners provides resources that help families assess these trade-offs in context. Questions to Ask a Trustee Before Engaging Before engaging a professional trustee in Hong Kong, families should ask several specific questions. What is the annual administration fee, and how does the trustee calculate it? What activities attract additional charges? How does the trustee structure distribution fees? What happens to fees if the asset base changes significantly? Are there minimum fee thresholds? Clear answers to these questions allow families to compare trustees accurately and to model Hong Kong trust costs over the expected life of the structure. Planning for Cost Efficiency Over Time Cost efficiency in trust administration improves when the family designs the structure well from the outset. A trust deed that clearly defines the trustee’s powers, the distribution policy, and the governance framework reduces the need for ongoing legal interpretation and dispute resolution. Similarly, a trustee who communicates proactively with beneficiaries reduces the likelihood of misunderstandings that escalate into formal disputes. Families who engage
Crypto Wealth and Cross-Border Estates: Why a Trust Reduces the Risk
Why Crypto Creates Unique Cross-Border Estate Complications Conventional cross-border estates are already complex. Each jurisdiction applies its own succession rules, tax treatment, and probate requirements. Adding cryptocurrency to that picture introduces a further layer of difficulty that most existing legal frameworks were not designed to handle. Cross-border crypto estates present challenges that go beyond the usual questions of which law governs which asset. Crypto is borderless by design, sitting on a global blockchain with no fixed location. However, estate administration is not borderless. The laws of multiple countries may claim jurisdiction over the same digital assets simultaneously, creating overlapping and sometimes conflicting obligations for executors and beneficiaries. The Situs Problem With Digital Assets In conventional estate planning, the location of an asset determines which country’s succession laws apply to it. French law governs property in France. Singaporean rules govern a bank account in Singapore. In this context, determining the legal location of a digital asset remains genuinely unsettled in many jurisdictions. Some countries look to the residence of the exchange where the asset sits. Others look to the residence of the holder. Still others have not addressed the question at all. This uncertainty means that the succession laws of multiple countries may claim the same crypto holding, each applying different rules about distribution, taxation, and transfer to heirs. Without a structured approach, administering these estates can consequently become legally contested and practically unworkable. Tax Exposure Across Multiple Jurisdictions Hong Kong abolished estate duty in 2006, which means crypto assets passing through a Hong Kong trust do not attract local inheritance tax. However, the tax position in other jurisdictions where the holder, the exchange, or the beneficiaries sit is a separate matter entirely. Many countries impose capital gains tax, inheritance tax, or income tax on distributions from foreign trusts or on assets transferred at death. For cross-border crypto estates, this means the same asset may attract tax in multiple jurisdictions simultaneously. The OECD tax transparency and exchange of information portal reflects the increasing international coordination of tax reporting, which makes undisclosed cross-border crypto holdings progressively harder to manage. Exchange Accounts and Cross-Border Access When a crypto holder dies with assets on a centralised exchange, the executor must satisfy that exchange’s internal procedures before accessing the account. This typically requires a death certificate, government-issued identification, and probate documents. Each exchange runs its own process, and many operate across multiple jurisdictions with different legal teams handling succession requests. Where multiple exchanges are involved, this creates a parallel administrative process in each jurisdiction where an exchange is based. Some platforms have introduced inheritance plan features, but these remain inconsistent across providers. Moreover, they do not resolve the underlying question of which country’s succession laws ultimately govern the distribution of the assets. How a Hong Kong Trust Simplifies the Picture When crypto assets sit within a trust administered in Hong Kong, the governance framework consolidates under a single legal structure. The trust deed governs how assets are managed and distributed. The trustee holds custody of the digital assets on behalf of the beneficiaries. At the settlor’s death, no conventional personal estate exists with respect to those assets, and no parallel succession proceedings arise in each jurisdiction where an exchange happens to be based. This structural consolidation is the primary advantage a Hong Kong trust offers for cross-border crypto estates. Rather than fragmenting administration across multiple countries and platforms, a single governed structure manages the assets and distributes them according to defined terms. The Hong Kong Trustee Ordinance Cap 29 provides the legal framework within which the trustee operates. Discovery and Identification of Crypto Holdings One of the most underappreciated risks in cross-border crypto estates is the failure to identify assets at all. Unlike bank accounts, which appear on financial statements and can be traced through estate administration processes, crypto holdings leave minimal visible trace. A holder who maintains self-custody wallets across multiple platforms may leave an estate where the full scope of digital asset holdings is never established. Executors increasingly encounter situations where families know that crypto holdings exist but cannot locate, access, or value them. In many cases, digital wealth is not lost because it had no value; it is lost because no plan was in place to identify and transfer it. A trust structure that holds digital assets during the settlor’s lifetime consequently eliminates this discovery problem entirely, since the trustee maintains a complete and current record of the trust’s asset base. The Role of Regulated Custody in Cross-Border Planning The security of digital assets held in a trust depends on the quality of the custody arrangement. For families managing this kind of estate, institutional custody through a regulated trustee provides continuity and security that personal wallets cannot match. The trustee’s own governance framework determines how assets are accessed and managed, rather than any individual’s knowledge of a seed phrase. Hong Kong’s regulatory framework for trust companies operates under the Anti-Money Laundering and Counter-Terrorist Financing Ordinance. This sets standards for how trustees manage client assets and maintain records. These standards apply equally to conventional and digital assets held within the trust structure. For these families, this regulatory oversight therefore provides an additional layer of assurance that the custody arrangement will function reliably over the long term. Coordinating With Advisors Across Jurisdictions Managing cross-border crypto estates requires coordination between the Hong Kong trustee and legal and tax advisors in each jurisdiction where the settlor, beneficiaries, or assets sit. The trustee administers the structure according to the trust deed and Hong Kong law. However, the tax consequences of distributions, the reporting obligations in each beneficiary’s country of residence, and the interaction between the trust structure and local succession laws all require local advice. The STEP Society of Trust and Estate Practitioners connects practitioners across jurisdictions who specialise in exactly these cross-border planning questions. Families with significant digital asset holdings distributed across multiple countries should consequently build a coordinated advisory team before establishing a trust structure, rather
Crypto Asset Succession: Why Personal Wallets Create Inheritance Risks
The Fundamental Problem With Crypto and Death Traditional financial assets have institutional safety nets. An executor can access a bank account with a death certificate and a grant of probate. A share registry can be updated through a legal process. Cryptocurrency held in a personal wallet works entirely differently. When the holder dies, the blockchain does not recognise death certificates, court orders, or legal succession. It simply waits for a cryptographic signature that will never come. This makes crypto asset succession one of the most practically challenging areas of modern estate planning. Families with significant digital asset holdings face risks that do not exist with conventional wealth, and those risks require specific structural solutions. What Happens to a Personal Wallet When the Owner Dies Control over a cryptocurrency wallet depends entirely on possession of the private key or seed phrase. These cryptographic credentials authorise transactions. When a holder dies without passing on these credentials, the assets become permanently inaccessible. There is no password reset, no help desk, and no legal mechanism that can recover access to a self-custody wallet without the original credentials. The problem is compounded by the fact that many crypto holders deliberately keep their seed phrases secret and in locations unknown to family members. The same security practices that protect assets during life become barriers to crypto asset succession at death. Furthermore, even where family members know that crypto holdings exist, they may have no idea where the assets sit, how much they are worth, or how to access them. The Risk of Writing Seed Phrases Into a Will A common but dangerous approach to crypto asset succession is including seed phrases or private keys directly in a will. This creates a serious security problem. When a will goes through probate, it becomes a public document. Any credentials included in the will are therefore exposed to the world at the moment probate opens, not just to the intended beneficiaries. A seed phrase made public in this way gives anyone who reads it immediate and irrevocable access to the wallet and all assets within it. This creates a situation where the two most common failure modes of crypto succession sit at opposite ends of the same problem. A seed phrase written into a will leaks to the world when probate opens. A seed phrase kept only in the holder’s head dies with them. A workable plan must therefore address both risks simultaneously. Why a Trust Structure Resolves the Access Problem When digital assets transfer into a trust held by a professional trustee, the trustee’s own succession rules govern what happens at the settlor’s death. The trustee continues to manage and control the assets according to the trust deed. The trust assets do not require probate, and the arrangement discloses no access credentials publicly. This is the most structurally clean solution to the crypto asset succession problem. The trustee holds the private keys or maintains custody arrangements through an institutional framework. When the settlor dies, the trustee continues to operate and distributes assets to the beneficiaries according to the trust deed. The process is consequently private, governed, and independent of any individual’s knowledge of a seed phrase. Hong Kong as a Base for Crypto Succession Planning Hong Kong offers several features that make it well-suited as the home jurisdiction for a trust structure holding digital assets. In Re Gatecoin Ltd, the Hong Kong Court of First Instance confirmed that cryptocurrencies constitute property capable of being held on trust. This provides the legal foundation for professional trustees to formally manage digital assets within a trust structure. Additionally, Hong Kong abolished estate duty in 2006, meaning crypto asset succession through a Hong Kong trust does not trigger local inheritance tax. The Hong Kong Trustee Ordinance Cap 29 provides the statutory framework within which trustees manage assets, and the TCSP licensing regime ensures that professional trustees meet defined standards of conduct. Cross-Border Complexity in Crypto Succession Crypto succession becomes significantly more complex when the holder is domiciled in one country, uses exchanges based in another, and leaves beneficiaries across multiple jurisdictions. Each jurisdiction may treat digital asset succession differently, and foreign tax authorities may impose their own inheritance or capital gains taxes on assets passing to beneficiaries resident in their jurisdiction. A Hong Kong trust structure consequently consolidates the governance of digital assets under a single legal framework. This reduces the need to open parallel succession proceedings in multiple jurisdictions and provides a clear governing law for how the assets are managed and distributed. The STEP Society of Trust and Estate Practitioners recognises this area of planning as a growing area of complexity for international families and provides guidance for practitioners navigating these cross-border issues. Practical Steps Before Transferring Crypto Into a Trust Transferring digital assets into a trust requires careful preparation. First, the settlor should prepare a complete inventory of all digital asset holdings, including the type of asset, the platform or wallet where it sits, and the approximate value. Second, the trust deed should expressly authorise the trustee to hold and manage digital assets. Third, the settlor and trustee must agree the custody arrangement, covering how the parties will hold private keys, who has access, and what security standards will apply. These steps involve more preparation than transferring conventional assets into a trust. However, they are necessary to ensure the succession plan functions as intended when it is needed. The Cost of Not Planning The cost of failing to plan for digital asset succession is not merely administrative inconvenience. It is the permanent loss of the assets themselves. Unlike a misplaced share certificate or a frozen bank account, no legal process can recover inaccessible crypto. The assets remain on the blockchain indefinitely, visible to anyone who looks but accessible to no one without the original credentials. For families where digital assets represent a significant portion of overall wealth, this risk is material. A trust structure with institutional custody and a properly
Hong Kong Trust Structures: Holding Digital Assets as Trust Property
Why Digital Assets Are Now a Serious Wealth Planning Consideration Digital assets have moved from speculative instruments into the mainstream wealth planning conversation. For high-net-worth individuals and internationally mobile families, cryptocurrency and other digital assets now form a meaningful part of the overall asset base. As a result, the question of how to hold, protect, and transfer these assets has become as pressing as the same question applied to property or business interests. Hong Kong trust structures offer a framework for addressing these questions. Understanding how digital assets interact with trust law in Hong Kong is therefore important for any family with significant crypto holdings. Hong Kong Courts Have Confirmed Crypto Is Trust-Capable Property A foundational question in digital asset planning is whether cryptocurrency can legally sit on trust at all. Hong Kong case law has clarified this point. In Re Gatecoin Ltd, the Court of First Instance confirmed that cryptocurrencies constitute property capable of being held on trust. This removes a significant area of legal uncertainty that previously made professional trustees cautious about accepting digital assets. This confirmation matters practically. It means a licensed trustee in Hong Kong can hold Bitcoin, Ethereum, and similar digital assets as part of a trust’s asset base, with the same fiduciary obligations that apply to conventional assets. Consequently, families can integrate digital assets into Hong Kong trust structures with a clear legal foundation supporting the arrangement. The TCSP Regime and Crypto Custody Professional trustees in Hong Kong operate under the Trust or Company Service Providers licensing regime. The Companies Registry administers this regime under the Anti-Money Laundering and Counter-Terrorist Financing Ordinance, setting standards for customer due diligence, record-keeping, and asset management. Notably, crypto custodians in Hong Kong that act as trustee of an express trust must hold a licence under the TCSP regime. This creates a regulated pathway for institutional custody of digital assets through a trust structure. Families using Hong Kong trust structures to hold digital assets should therefore ensure their trustee holds the appropriate licence and understands the specific operational requirements of managing crypto alongside conventional assets. How Digital Assets Differ From Conventional Trust Assets Holding digital assets within a trust introduces practical challenges that do not apply to conventional assets. Custody presents the most significant challenge. Control over digital assets depends on the secure management of private keys and seed phrases. Unlike a bank account or share register, there is no institutional safety net if access credentials are lost or compromised. Loss is permanent and irreversible. Furthermore, digital assets do not generate income in the conventional sense. This requires trustees to consider their impact on the duty of impartiality between income and capital beneficiaries. Valuation also presents challenges, since crypto prices are highly volatile. The trustee must apply a consistent and defensible valuation methodology when reporting asset values to beneficiaries or for tax purposes. Investment Duties and Digital Assets Trustees holding digital assets within Hong Kong trust structures remain subject to the same investment duties that apply to all trust assets. The Hong Kong Trustee Ordinance Cap 29 requires trustees to act as a prudent person of business when making investment decisions. This standard applies whether the asset is a listed equity or a cryptocurrency. In practice, this means the trustee must consider the suitability of holding digital assets within the overall trust portfolio. Concentration risk, volatility, liquidity, and the investment mandate set out in the trust deed are all relevant factors. Moreover, a trustee who holds an excessive proportion of the trust’s assets in highly volatile digital assets without documented justification may face questions about whether they met the prudent investor standard. Security Standards for Digital Asset Custody The Hong Kong Securities and Futures Commission has introduced custody standards for licensed virtual asset trading platforms, covering cold wallet operations, senior management accountability, and real-time threat monitoring. These standards apply directly to licensed trading platforms rather than private trust structures. However, they reflect the broader regulatory expectation for how institutions should secure digital assets. Trustees should apply comparable security standards when holding digital assets within Hong Kong trust structures. This includes using cold wallet storage for the majority of holdings, maintaining clear access control procedures, and documenting protocols for key management. These measures protect the trust’s assets and demonstrate that the trustee meets their duty of care to the beneficiaries. Integrating Digital Assets Into the Trust Deed When establishing Hong Kong trust structures that will include digital assets, the trust deed should address several specific considerations. These include defining what categories of digital assets the trustee can hold, setting out the custody and security standards expected of the trustee, specifying the valuation methodology to apply, and addressing how the trustee should handle distributions where a beneficiary wants crypto rather than fiat currency. A trust deed that does not address these matters may leave the trustee without clear authority to act in certain situations. This creates administrative uncertainty and potential disputes with beneficiaries. Engaging legal advisors experienced in both trust law and digital asset structuring is therefore important when drafting or amending a deed to accommodate crypto holdings. Planning for Regulatory Evolution Hong Kong’s regulatory framework for digital assets continues to develop rapidly. Legislation targeting virtual asset dealers and custodians is expected to progress through the Legislative Council in 2026. These developments may affect how regulators and compliance teams treat digital assets held within trust structures. Families using such structures to hold digital assets should consequently build a regular review process into their governance framework. This ensures the structure remains compliant as the regulatory environment evolves. The STEP Society of Trust and Estate Practitioners provides ongoing guidance for professionals navigating the intersection of trust law and digital asset management.
Family Governance and Trusts: Structuring Decisions Across Generations
Why Governance Becomes Critical as Family Wealth Grows Managing wealth across generations is as much a governance challenge as it is a financial one. As families grow larger and more geographically dispersed, decision-making becomes harder to coordinate. Disagreements about how assets should be managed, who benefits, and how control passes from one generation to the next can create conflict that undermines the very wealth structure the family built. Family governance and trusts address this challenge by creating formal frameworks for decision-making that operate independently of any single family member’s preferences or personality. What Family Governance Means in Practice Family governance refers to the systems, structures, and processes a family uses to make collective decisions about shared wealth. It covers questions such as who participates in investment decisions, how disputes are resolved, what values guide the family’s approach to wealth, and how the next generation prepares to take on responsibility. In the context of family governance and trusts, these systems work alongside the legal framework provided by the trust deed. The trust deed defines the trustee’s powers and the beneficiaries’ rights. The governance framework defines how the family interacts with the trustee and with each other around those legal structures. The Trust as a Governance Anchor A well-structured trust provides a natural anchor for family governance. It separates legal ownership from beneficial interest, which removes the need for consensus on every asset management decision. The trustee holds legal title and manages assets according to the deed. Beneficiaries receive distributions according to the trust’s terms. This separation reduces the friction that often arises when family members hold assets jointly or through shared personal ownership structures. Furthermore, the trust deed can include provisions that formalise governance arrangements. These might cover how a family investment committee operates, how the protector is appointed, and under what circumstances the trustee must consult the family before making significant decisions. Family Constitutions and Their Role Many families that use trusts as part of their wealth structure also develop a family constitution. This is a document that sets out the family’s shared values, principles, and expectations around wealth management. It is not legally binding in the same way as a trust deed, but it provides a reference point for resolving disagreements and guiding trustee decision-making. A family constitution might address topics such as the family’s investment philosophy, how new family members are introduced to the governance structure, how younger generations are educated about the family’s wealth, and what responsibilities come with being a beneficiary. The STEP Society of Trust and Estate Practitioners represents professionals who advise families on developing these frameworks alongside their formal trust structures. Generational Transition and Governance Design One of the most important functions of family governance and trusts is managing the transition of decision-making authority from one generation to the next. The founding generation typically holds strong views about how wealth should be managed. Subsequent generations may have different priorities, risk appetites, and financial needs. A governance framework that anticipates this transition builds in mechanisms for the next generation to participate gradually. This might include observer roles on family committees, structured education programmes about the trust’s assets and history, or defined criteria that must be met before a family member takes on a more active governance role. Gradual participation reduces the risk of abrupt and poorly managed handovers that destabilise the trust’s administration. The Protector’s Role in Family Governance The protector is one of the most important governance roles within a trust structure. In the context of family governance and trusts, the protector acts as a bridge between the family and the trustee. They provide oversight of the trustee’s decisions without giving the family direct legal control over trust assets. Choosing the right protector is therefore a significant governance decision. Some families appoint an independent professional to this role to ensure neutrality. Others appoint a senior family member who is not a beneficiary. Each approach has different implications for how governance disputes are managed and how the family’s interests are represented over time. Dispute Resolution Within Governance Frameworks Disputes among family members about trust arrangements are not uncommon. They may arise over distribution decisions, investment strategies, or the conduct of the trustee. A well-designed governance framework includes defined processes for raising and resolving these disputes before they escalate to formal legal proceedings. These processes might include mediation provisions, the role of the protector as a first point of escalation, or the appointment of an independent advisor to review specific decisions. The Hong Kong Mediation Ordinance Cap 620 provides a statutory basis for formalising mediation arrangements in trust governance documents where parties wish to adopt this approach. Communicating Governance Expectations to Beneficiaries One practical challenge in family governance and trusts is ensuring that beneficiaries understand the governance framework and their role within it. Beneficiaries who do not understand why decisions are made in certain ways, or who feel excluded from the process, are more likely to challenge trustee decisions or create conflict within the family. Regular communication between the trustee and the beneficiaries is therefore an important governance tool. This might take the form of annual family meetings, written updates on the trust’s investment performance and distribution policy, or one-on-one conversations between the trustee and individual beneficiaries about their circumstances and expectations. Adapting Governance Structures Over Time Family governance and trusts must evolve as the family itself changes. A governance framework designed for a small first-generation family may not suit a larger third-generation family spread across multiple countries. Regular reviews of the governance structure help ensure it remains practical and effective. The Hong Kong Trustee Ordinance Cap 29 provides the legal foundation within which trust governance arrangements in Hong Kong operate, and any amendments to governance structures must remain consistent with its provisions. Building in a formal review process from the outset makes adjustments easier to manage and reduces the risk of governance structures becoming outdated and ineffective over time.
Trust Distribution Planning: How Trustees Manage Beneficiary Needs
Why Distribution Decisions Are Central to Trust Administration A trust’s primary function is to hold and manage assets for the benefit of its beneficiaries. How and when those assets flow to beneficiaries is therefore one of the most consequential aspects of trust administration. Trust distribution planning is the process by which trustees assess beneficiary needs, apply the terms of the trust deed, and make decisions that serve both current and future beneficiaries fairly. This process requires judgement, documentation, and a clear understanding of the trustee’s legal duties. It also requires a long-term perspective that balances present needs against the preservation of the trust’s asset base. The Trust Deed as the Starting Point Every trust distribution planning decision begins with the trust deed. The deed defines who the beneficiaries are, what powers the trustee holds over distributions, and whether any mandatory payments apply. In a discretionary trust, the trustee holds wide powers to decide the timing, amount, and recipient of distributions. In a fixed interest trust, the beneficiaries’ entitlements are defined and the trustee has less room for discretion. Trustees must act within the powers the deed grants. Distributions made outside those powers may constitute a breach of trust, exposing the trustee to personal liability. Therefore, a thorough understanding of the deed is the foundation of any sound distribution process. Assessing Beneficiary Needs In discretionary trusts, trustees typically consider several factors when assessing beneficiary needs as part of trust distribution planning. These include the beneficiary’s financial position, their age and life stage, the purpose of the requested distribution, and the impact on other beneficiaries if a significant distribution goes to one individual. Trustees may request financial information from beneficiaries to support their assessment. While beneficiaries are not always obliged to provide this, doing so helps the trustee make well-informed decisions. The letter of wishes left by the settlor also guides this process, particularly where the settlor expressed preferences about how different beneficiaries should be treated. Balancing Current and Future Beneficiaries One of the more complex aspects of trust distribution planning is balancing the interests of current beneficiaries against those of future beneficiaries. A large distribution today reduces the assets available to future generations. Conversely, an overly conservative approach may leave current beneficiaries without support they genuinely need. Professional trustees approach this balance by considering the trust’s overall investment strategy alongside its distribution policy. The STEP Society of Trust and Estate Practitioners represents professionals who work across exactly this area, and its published guidance outlines how trustees should document their reasoning when making decisions that affect this balance. Clear documentation protects the trustee and demonstrates that all beneficiaries’ interests were genuinely considered. Types of Distributions and Their Uses Trust distributions take several forms, and each serves a different purpose within trust distribution planning. Income distributions pass earnings from trust investments to beneficiaries on a regular basis. Capital distributions transfer a portion of the trust’s principal assets to a beneficiary, often for a specific purpose such as purchasing property or funding a business. Loans from the trust to a beneficiary are another available tool in some structures. Unlike a distribution, a loan must be repaid and may carry interest. This approach can provide liquidity to a beneficiary without permanently reducing the trust’s asset base. Trustees should document loan arrangements carefully to avoid tax authorities recharacterising them as distributions. Tax Considerations in Distribution Planning Tax consequences affect trust distribution planning significantly. The tax treatment of a distribution depends on the nature of the payment, the jurisdiction of the trust, and the tax residence of the beneficiary. In many countries, income distributions from a foreign trust attract income tax in the beneficiary’s hands. Capital distributions may be subject to capital gains tax or treated as income depending on local rules. Trustees administering Hong Kong trusts should coordinate with beneficiaries’ local tax advisors before making significant distributions. The OECD tax transparency and exchange of information portal explains how distribution information reported by financial institutions may reach tax authorities in the beneficiary’s country of residence. Consequently, undisclosed distributions carry significant compliance risk. The Role of Distribution Committees and Family Councils Some family trusts establish a distribution committee or family council to provide input into the trustee’s decision-making process. This structure allows family members to participate in governance without giving them direct control over the trustee’s decisions. The trustee retains ultimate authority but benefits from the family’s knowledge of individual beneficiary circumstances. This approach is particularly useful in larger families where the trustee may not have direct visibility into every beneficiary’s financial situation. However, any committee or council arrangement must be structured carefully to avoid giving beneficiaries legal control that could undermine the trust structure. Documenting Distribution Decisions Documentation is a critical part of trust distribution planning. Trustees should maintain written records of every distribution decision, including the factors considered, the information reviewed, and the reasoning applied. This documentation serves several purposes. First, it demonstrates that the trustee acted within their powers and in good faith. Second, it provides a record for review by beneficiaries or the court if a decision is later challenged. Third, it supports the trustee’s position in any tax authority inquiry about the nature of a distribution. The Hong Kong Trustee Ordinance Cap 29 underpins the legal obligations of trustees operating in Hong Kong, and professional trustees maintain these records as part of their standard administration process. Reviewing Distribution Policy Over Time Trust distribution planning is not a one-time exercise. Family circumstances change, asset values fluctuate, and beneficiaries move through different life stages. A distribution policy that suited the trust’s early years may need adjustment as the trust matures and the beneficiary class evolves. Regular reviews between the trustee, the protector where one exists, and the family’s advisors help ensure the distribution framework remains appropriate. These reviews also provide an opportunity to update the letter of wishes if the settlor’s preferences have changed, and to assess whether the trust’s investment strategy continues to support
Hong Kong Trust Compliance: Reporting Duties for Foreign Settlors
What Foreign Settlors Need to Understand About Compliance Establishing a trust in Hong Kong does not remove a settlor’s obligations in their country of residence. Most countries require their tax residents to report foreign trust arrangements, regardless of where the trust is administered. Hong Kong trust compliance covers the obligations that apply within Hong Kong itself, but foreign settlors must also navigate the reporting requirements of their home jurisdictions. Understanding both sides of this compliance picture is essential before establishing a structure and throughout its life. How Hong Kong Regulates Trust Arrangements Hong Kong does not impose a specific trust registration requirement for private trusts. However, professional trustees operating in Hong Kong must hold a licence under the Trust or Company Service Providers regime. This means the trustee itself operates under regulatory supervision, even where the trust deed does not require separate registration. Hong Kong trust compliance for the trustee includes maintaining proper records, conducting customer due diligence on settlors and beneficiaries, and meeting anti-money laundering obligations under the Anti-Money Laundering and Counter-Terrorist Financing Ordinance. Foreign settlors should expect to provide detailed documentation about the source of assets transferred into the trust. The Common Reporting Standard and Its Reach The Common Reporting Standard is the most significant international compliance framework affecting foreign settlors who use Hong Kong trusts. Under this framework, financial institutions in participating jurisdictions automatically exchange account information with tax authorities in the account holders’ countries of residence. Hong Kong participates in the automatic exchange of financial account information coordinated through the OECD tax transparency and exchange of information portal, and has activated exchange relationships with a growing number of jurisdictions. As a result, information about trust arrangements administered in Hong Kong may reach tax authorities in the settlor’s country of residence. Foreign settlors should assume their home tax authority receives this information and plan accordingly. Reportable Jurisdictions and Settlor Residence The reporting obligations a foreign settlor faces depend primarily on their country of tax residence. Different countries treat foreign trust arrangements in different ways. Some require annual disclosure of the trust’s existence, its assets, and any distributions received. Others require the settlor to report income or gains arising within the trust as though those amounts were their own. For example, settlors resident in the United States must comply with IRS reporting requirements for foreign trusts, including Forms 3520 and 3520-A. Settlors in the United Kingdom must disclose foreign trust arrangements to HMRC and may face attribution of trust income under anti-avoidance provisions. Settlors in other jurisdictions face their own distinct sets of obligations. Hong Kong trust compliance on the trustee’s side does not substitute for these home jurisdiction obligations. Foreign settlors are responsible for understanding and meeting their own reporting duties independently. Anti-Money Laundering Obligations and Source of Funds One area where Hong Kong trust compliance directly affects foreign settlors is in the onboarding process. Licensed trustees in Hong Kong must conduct thorough due diligence on all parties to a trust arrangement. This includes verifying the identity of the settlor, understanding the source of funds transferred into the trust, and assessing the purpose of the arrangement. Settlors transferring significant assets into a Hong Kong trust should be prepared to provide documentation supporting the legitimate origin of those assets. This may include corporate records, sale agreements, inheritance documentation, or other evidence depending on the nature of the assets. The Hong Kong Monetary Authority publishes supervisory standards that apply across the financial sector, including trust service providers, covering anti-money laundering and customer due diligence requirements. Beneficial Ownership Transparency International standards on beneficial ownership transparency have tightened considerably over the past decade. Hong Kong has implemented measures requiring trust service providers to maintain records of the beneficial owners of trusts they administer. Regulatory authorities can access this information on request. Foreign settlors should understand that beneficial ownership information is not fully private. While Hong Kong does not maintain a public register of trust beneficial owners, regulatory authorities can access this information in the context of investigations or information exchange requests. Furthermore, the trustee’s own due diligence records create a documented trail of ownership and control. Substance and Residency Considerations Some jurisdictions assess whether a trust has genuine substance in its stated home jurisdiction. A Hong Kong trust administered by a licensed professional trustee with real decision-making authority based in Hong Kong is generally in a stronger position than a structure where effective management takes place elsewhere. Foreign settlors who retain significant control over trustee decisions, or where the trust’s effective management occurs in the settlor’s home country, may find that their home jurisdiction treats the trust as locally resident for tax purposes. This is one reason why genuine Hong Kong trust compliance, including proper trustee involvement in decision-making, matters beyond mere administrative formality. Practical Steps for Foreign Settlors Foreign settlors should take several practical steps to manage their compliance position effectively. First, they should obtain advice from a tax advisor in their country of residence who understands the treatment of foreign trusts under local law. Second, they should understand what information their Hong Kong trustee will report under the Common Reporting Standard and to which jurisdictions. Third, they should maintain clear records of all transfers into and distributions from the trust. Additionally, settlors should review their compliance position periodically. Changes in tax residency, family composition, or the trust’s asset base can all affect reporting obligations. Regular communication between the Hong Kong trustee and the settlor’s home jurisdiction advisors helps ensure that Hong Kong trust compliance and home jurisdiction obligations remain aligned. Staying Ahead of Regulatory Change The international regulatory environment for cross-border trust arrangements continues to evolve. New information exchange agreements, updated anti-money laundering standards, and changes to domestic tax legislation in key jurisdictions can all affect the compliance position of foreign settlors using Hong Kong trusts. The Financial Action Task Force sets the international baseline on anti-money laundering and counter-terrorist financing that most major jurisdictions, including Hong Kong, incorporate